Correlation-Adjusted Allocation Models for Overlapping Horse Racing and Poker Tournament Events
Willa Hansen · Sep 25, 2026
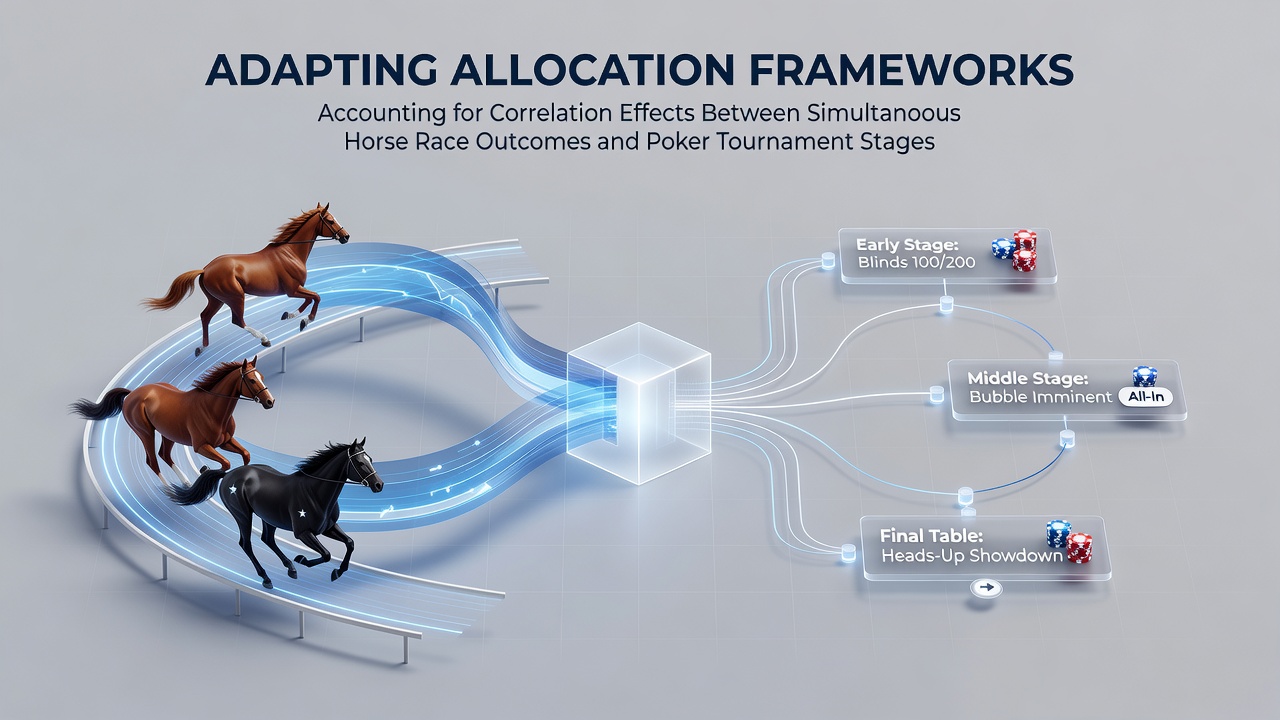
Correlation-Adjusted Allocation Models for Overlapping Horse Racing and Poker Tournament Events
Allocation frameworks in betting environments have evolved to handle simultaneous outcomes across horse racing and poker tournaments, where correlation effects arise from shared timing, participant psychology, and market liquidity patterns. Researchers track these overlaps through covariance matrices that quantify how a late surge in one race influences stack pressures in concurrent tournament levels. Data from multi-event platforms indicate that ignoring these links leads to overexposure during clustered high-variance periods.
Statistical Foundations of Cross-Event Correlations
Analysts construct correlation matrices by combining historical finish positions from horse races with payout distributions from poker stages that overlap in real time. Studies published in the Journal of Gambling Studies demonstrate that positive correlations frequently emerge when favorite horses shorten in the betting ring at the same moment short stacks face all-in decisions on adjacent tables. Negative correlations appear when long-shot winners in races coincide with double-up opportunities that stabilize poker fields. These patterns allow modelers to adjust position sizes through modified Kelly formulas that incorporate off-diagonal covariance terms rather than treating each wager as independent.
September 2026 brought fresh datasets from North American and European exchanges that refined these matrices, revealing stronger links during evening sessions when US tracks and major online poker series run in parallel. Observers note that liquidity shifts in one market often precede volatility spikes in the other by five to fifteen minutes, creating measurable lead-lag relationships suitable for predictive allocation.
Framework Adaptation Techniques
Portfolio managers adapt traditional mean-variance optimization by replacing scalar variance inputs with full covariance structures that span both domains. One approach replaces separate bankroll silos with a unified exposure limit calibrated to the joint probability of drawdowns. Monte Carlo simulations sample thousands of race and hand outcomes simultaneously, then rebalance stakes according to the realized correlation surface. Those who have implemented these methods report smoother equity curves because extreme joint losses occur less often than independent models predict.
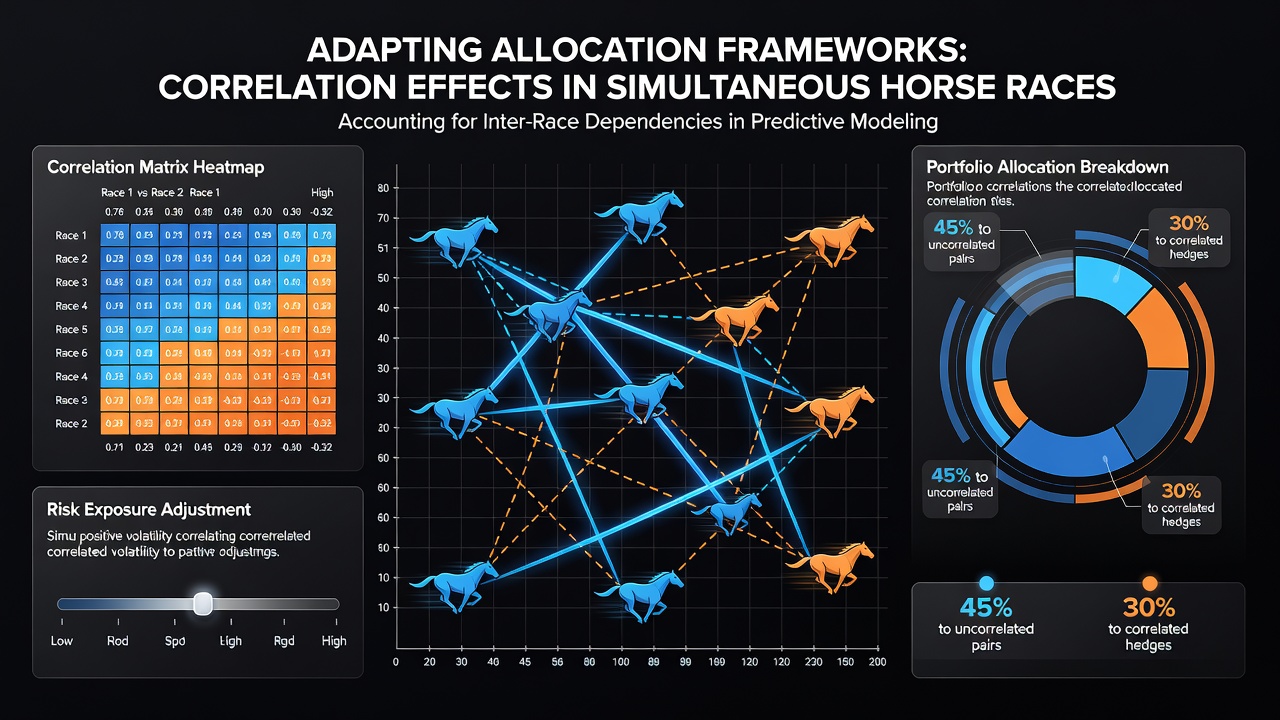
Another technique applies dynamic scaling factors derived from rolling correlation estimates updated every fifteen minutes. When correlation exceeds a threshold, total stake across both activities contracts proportionally; when it drops, capacity expands. Academic work from the University of Sydney's gambling research unit shows this rule reduces tail-risk measures by measurable percentages while preserving expected growth rates under moderate dependence.
Practical Implementation Examples
Consider a bettor active during a Saturday card that features four overlapping UK and Irish race meetings alongside a large-field poker tournament. The model first calculates individual edge estimates for each horse and each tournament level, then multiplies the resulting vector by the inverse of the correlation matrix to produce adjusted weights. This step automatically reduces exposure to correlated favorites while increasing allocation to decorrelated long shots or deep-run probabilities. Execution occurs through automated APIs that enforce the revised limits before each race off or hand deal.
Similar logic applies during WSOP circuit events that coincide with major US racetracks. Data indicate that afternoon prelims often exhibit weaker correlations with early race cards, allowing larger combined positions, whereas evening final tables align more closely with feature races and require tighter overall constraints. Regulators in several jurisdictions have begun requesting disclosure of these joint-risk models as part of operator licensing reviews.
Data Sources and Validation
Validation relies on out-of-sample testing across multiple seasons. Researchers compare realized portfolio volatility against predictions from both correlated and uncorrelated frameworks. Consistent gaps appear in favor of the correlated version, particularly around major festivals where simultaneous scheduling intensifies. Industry groups such as the European Gaming and Betting Association have circulated anonymized case studies illustrating the magnitude of these improvements without revealing proprietary parameters.
Further refinement incorporates macroeconomic indicators that affect both racing attendance and online poker traffic. When fuel prices or currency movements alter discretionary spending patterns, correlations strengthen across leisure gambling verticals. Models that embed these external variables produce allocation schedules that adapt ahead of observable market shifts rather than reacting after the fact.
Conclusion
Allocation frameworks that embed correlation effects between simultaneous horse race outcomes and poker tournament stages deliver more accurate risk estimates than isolated calculations. Operators and individual participants who integrate covariance structures, rolling updates, and joint simulation routines maintain exposure within predefined limits even when events cluster. Continued refinement of these methods, supported by expanding datasets through late 2026, supports stable growth across combined betting activities.